


(DMI) reaches record high in 3rd quarter of 2025, with year-on-year growth increasing by an impressive 7.4%
Drive.co.za has released the findings of the Drive Motor Index (DMI) for the 3rd quarter of 2025, which remains on an upward year-on-year trajectory. The DMI is also higher than prior to the Covid-19 pandemic.
The DMI is a monthly barometer of business conditions in the motor sector, compiled by renowned economist Dr Roelof Botha, a long-standing adjunct faculty member at GIBS and economic advisor to the Optimum Investment Group and Drive.co.za. The DMI is a composite index that measures the real percentage change in key indicators of the motor vehicle industry (including manufacturing and sales of vehicles and associated indicators). It comprises twelve different indicators, weighted according to their perceived importance in gauging the overall state of the motor sector in South Africa.
Drive.co.za is one of the nine fastest growing mid-size companies on the African continent and has recently won a Financial Times award for this achievement. Drive.co.za represents a seamless car subscription approach to permanently driving a new car, without the frustrations of legal ownership. This concept has fairly recently been adopted in South Africa and is based on a business model that has been successful in several highincome countries. It eliminates, inter alia, the need for bank credit applications and several other administrative tasks associated with personal car ownership, including licensing, traffic offences and insurance.
RESULTS of the DMI for the 3rd quarter of 2025
Following a negative trend in the DMI induced by the highest interest rates in 15 years, the first rate cut (in September 2024) immediately led to a return of upward momentum in most of the key indicators underpinning the DMI (see figure 1). This was followed by five more rate cuts of 25 basis points each, resulting in a prime rate of 10.5% as at the end of September. Another rate cut of 25 basis points occurred during the 4th quarter of 2025.
The welcome decline in the prime rate from a high of 11.75% that lasted for 16 months (from May 2023 to September 2024) to 10.5% at the end of September 2024 has predictably encouraged buying activity in the motor vehicle sector, especially for new vehicle sales. Apart from the lower financing costs induced by the rate-cutting cycle, a substantial increase in the imports of relatively cheap motor vehicle models from China has also served to stimulate motor trade sales.
A particularly encouraging feature of the DMI for the 3rd quarter of 2025 is the fact that nine of the twelve indicators comprising the index experienced positive year-on-year growth during the 3rd quarter of 2025, including two of the ‘big-ticket’ indicators that enjoy a large weighting in the DMI, namely new vehicle sales and the number of vehicles sold. This exceptionally strong growth trend was matched by the quarter-on-quarter performance of the latter two indicators, with vehicle & component exports and the value of used vehicle sales also recording real quarter-on-quarter growth (see table 1).
It should be noted that the recovery of the automotive industry is still in its infancy, as the combination of the Covid-19 lockdowns and the subsequent record high interest rates wreaked havoc with economic growth, ultimately leading to a decline in the real disposable incomes of households. Although the DMI has fared slightly better than South Africa’s real GDP growth since 2018 (see table 2), the average annual increase in the DMI since its inception in 2018 remains muted by emerging market standards.
The upward trajectory for the number of local vehicle sales reached a record high during the 3rd quarter of 2025. Figure 2 shows the sharp decline during the worst of the Covid-19 pandemic, followed by a remarkably swift recovery to virtually the same level as prior to Covid, mainly as a result of pent-up demand and the fact that the prime rate was lowered from 10% to 7%.
Unfortunately, the Monetary Policy Committee (MPC) of the Reserve Bank then went on a rate-hiking spree that ultimately resulted in an increase of 68 % in the cost of credit (as measured by the prime rate), which predictably resulted in another downward trend in the DMI. The positive impact of the subsequent lowering of the prime rate (via the repo rate) has now resulted in a new record high for the DMI (since its base period of 2018 ).
Hopefully, the recent decision to lower the upper level of the inflation target range from 6% to 4% will not prompt resistance from the MPC to lower interest rates further (the bottom level remains at 3%). As long as the rand exchange rate retains its current level against the US dollar, inflation is bound to remain under control.
The ample early summer rains in the country's maize producing regions could also play a part in keeping food prices in check.
Another outstanding feature of the latest data underpinning the DMI is the new record high for the real value of exports of vehicles and components during the 3rd quarter of 2025 (Figure 3). This has occurred despite the uncertainty surrounding the so-called “Trump tariffs” and the relatively slow transition to electric vehicle manufacturing in South Africa (including hybrids). In the meantime, exports of vehicles and components remain the third-largest contributor to South Africa’s goods export earnings.
BACKGROUND to the Drive Motor Index (DMI)
One of the reasons for the decision by Drive.co.za to undertake the research underpinning the index is the fact that different indicators relating to the motor industry often contradict each other within a particular month or even quarter. A need clearly existed for an overall time-series gauge of business conditions in this crucial sector, which makes a substantial contribution to South Africa’s GDP.
South Africa is fortunate to possess an independent, multi-brand automotive industry (including distribution, servicing and repairs). This sector plays an indispensable role in providing mobility to the whole population, promoting consumer choice, maintaining vehicles on the country’s roads and providing ample facilities for refuelling and convenience store shopping.
Based on data from Statistics SA and Naamsa, key macroeconomic characteristics include:
- The automotive industry contributes an estimated 4.9% to GDP (2.9% manufacturing, 2% retail).
- Manufacturing + retail + multiplier effects support ~580,000 jobs in South Africa.
- Since 1994, approximately R130 billion has been invested in the industry by domestic OEMs.
- Vehicle & component manufacturing is South Africa’s largest manufacturing sector — contributing 17.7% of factory output (R537 billion in 2023).
- In 2023, exports of vehicles & components totalled R240 billion, the third-largest source of foreign exchange after minerals and precious metals.
Against this background, the DMI’s current and future trends should be taken seriously by policymakers to prevent job losses and maintain South Africa’s global competitiveness.
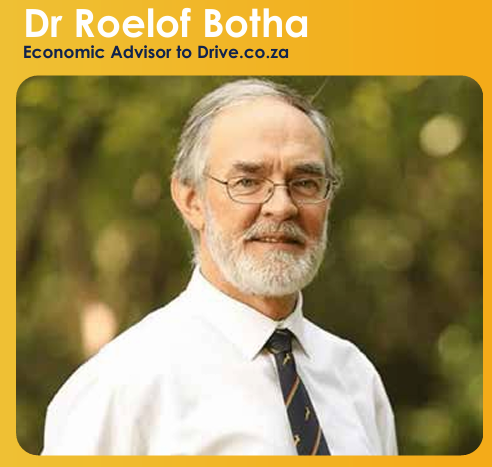 Botha delivers engaging keynote speeches on the country’s economic and political landscape. With over 40 years’ experience, he is a lecturer, financial editor, columnist and researcher.
He is a former Finmedia Economist of the Year and teaches part-time at GIBS, while advising the Optimum Financial Services Group.
Beyond economics, he enjoys cricket, soccer coaching and skydiving. His eldest son, also Dr Roelof Botha, has made major contributions in Silicon Valley — co-founding PayPal and helping drive YouTube’s acquisition by Google.